Eastside Mortgage Rate Advisory — October 2026 (Buyers and Sellers)
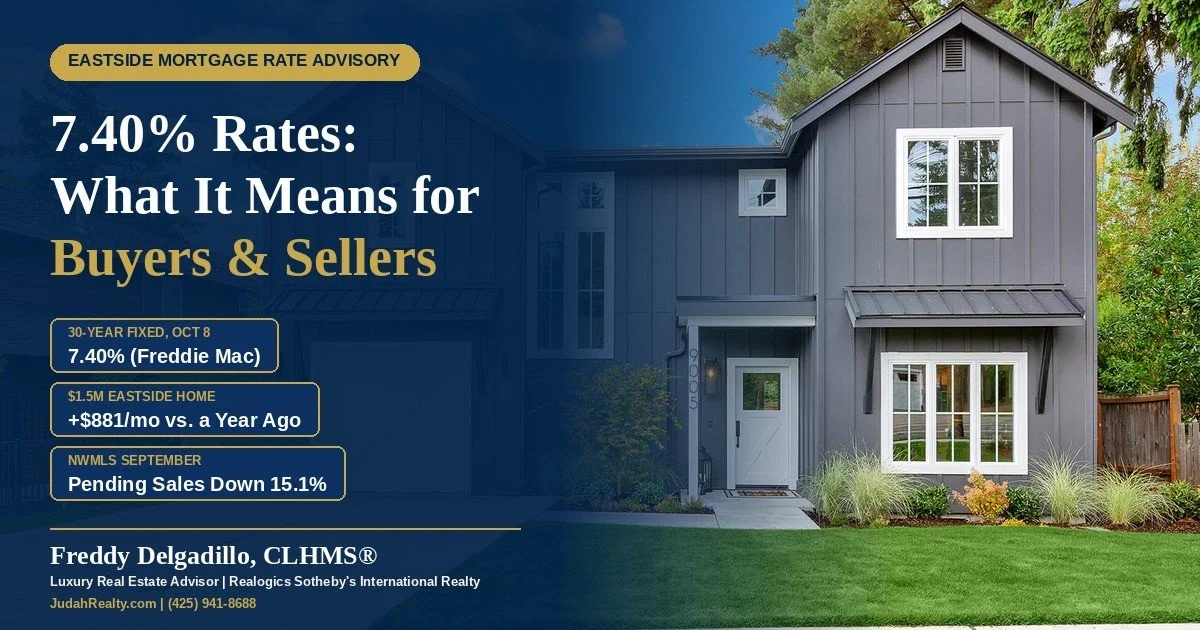
What 7.40% Mortgage Rates Mean for Eastside Home Buyers and Sellers
THE SHORT ANSWER
The 30-year fixed mortgage rate reached 7.40% on October 8, 2026, up from 6.30% a year ago (Freddie Mac). On a hypothetical $1.5 million Eastside purchase with 20% down, that raises principal and interest from about $7,428 to $8,309 per month, an extra $881, or about $10,572 a year. At the same monthly payment as a year ago, a buyer's purchasing power falls by about $159,000. For sellers, higher rates mean fewer qualified buyers per listing, so pricing and presentation matter more.
Where Mortgage Rates Stand Right Now
Freddie Mac's weekly Primary Mortgage Market Survey puts the average 30-year fixed rate at 7.40% for the week ended October 8, 2026. That is up from 7.28% the week before and 6.30% a year ago. The 15-year fixed average is 6.73%.
The climb has been steady. NWMLS reported the 30-year rate moving from 6.71% on September 3 to 7.03% on September 24, and it has kept climbing through the October 8 reading. Teaching point: Freddie Mac's number is a national average of applications from borrowers with strong credit and a 20% down payment. Your own rate depends on credit, down payment, loan size, and the lender, and larger jumbo loans can price differently from the averages.
The $1.5 Million Payment Test
Rates are abstract until you see them as a monthly payment. Here is a hypothetical Eastside purchase: a $1,500,000 home with 20% down ($300,000), a $1,200,000 loan, and a 30-year fixed rate. The chart shows principal and interest only, using Freddie Mac's rate on each date.

| 30-Year Fixed Rate | Monthly Principal & Interest | Change vs. 6.30% | Change per Year |
|---|---|---|---|
| 6.30% (Oct 2025) | $7,428 | — | — |
| 6.71% (Sep 3, 2026) | $7,751 | +$323 | +$3,876 |
| 7.03% (Sep 24, 2026) | $8,008 | +$580 | +$6,960 |
| 7.28% (Oct 1, 2026) | $8,211 | +$783 | +$9,396 |
| 7.40% (Oct 8, 2026) | $8,309 | +$881 | +$10,572 |
Hypothetical example. Principal and interest only; excludes property taxes, homeowners insurance, HOA dues, and mortgage insurance. Not a loan offer or rate quote.
What the Numbers Mean
- +$881 per month. Same home, same down payment, same loan amount. The only change is the rate.
- Purchasing power drops about $159,000. The $7,428 payment that supported a $1.2 million loan at 6.30% supports only about $1.07 million at 7.40%. With 20% down, that is a home price near $1.34 million instead of $1.5 million.
- Lifetime interest rises about $317,000 if the loan is held for the full 30 years ($1.79 million versus $1.47 million). Most borrowers sell or refinance sooner, but it shows how much a rate point carries.
- 10% down is tighter. On a $1.35 million loan the payment moves from about $8,356 to $9,347, roughly $991 more per month.
How Rates Show Up in the Market Data
Higher payments shrink the pool of buyers who qualify, and that shows up in contracts. NWMLS reported that pending sales fell 15.1% in September, the sharpest year-over-year decline of 2026, while active listings rose 24.5% to 24,965. For every 100 new listings added, buyers went under contract on about 62 homes, down from about 80 a year earlier.
On the Eastside, the nine NWMLS single-family areas combined showed active listings up 47.4% and pending sales down 18.9% from last September. West Bellevue is the only buyer's market at 8.32 months of supply, while Bellevue East is the tightest at 3.27. See the full city-by-city September breakdown →
Teaching point: rates are one factor, not the only one. They tend to act as a brake on demand, which raises inventory and months of supply, which then gives buyers more negotiating room. Steven Bourassa of the Washington Center for Real Estate Research calls the price response "downward stickiness": prices fall more slowly than they rise because sellers can often wait rather than accept less.
What This Means for Sellers
- Price to today's closed sales. Eight of nine Eastside areas posted lower medians than a year ago in September, and Bellevue East was flat. Last spring's sale of a neighbor is not today's comparable.
- Plan for fewer showings. NWMLS reports 4.2 showings per listing across its region in September versus 5.2 a year ago, so presentation, photography, and pricing at launch matter more.
- Consider buyer-side incentives. A seller credit toward closing costs or a rate buydown can lower a buyer's monthly payment. Ask a lender what a buydown would cost and compare it with the equivalent price reduction.
- If you have a low rate, run the move-up math. A seller with a rate near 3% or 4% faces a higher payment on the next home. That is real, so we compare the full cost of moving with the cost of staying before you list.
What This Means for Buyers
- Shop by payment, not price. Decide the monthly payment you are comfortable carrying, then work backward to a price. The table above shows how a rate change moves that number.
- Get quotes from more than one lender. Freddie Mac's chief economist has encouraged borrowers to compare lenders, and rate and fee differences add up over the life of a loan.
- Use the inventory. Across the NWMLS region, more homes are for sale than at any point since 2014, which can give you room to negotiate on price, repairs, credits, or timing.
- Don't try to time the market. If rates fall later you may be able to refinance, but that is never guaranteed. A home you can carry comfortably today is the safer foundation.
Frequently Asked Questions
What are mortgage rates today in October 2026?
Freddie Mac reported the average 30-year fixed mortgage rate at 7.40% for the week ended October 8, 2026, up from 7.28% the prior week and 6.30% a year earlier. Freddie Mac updates its national average every Thursday, and rates quoted for individual borrowers and larger jumbo loans can differ.
How much more does a $1.5 million Eastside home cost per month at 7.40%?
On a hypothetical $1.5 million purchase with 20% down ($1.2 million loan, 30-year fixed), principal and interest is about $8,309 per month at 7.40% versus about $7,428 at last year's 6.30%. That is about $881 more per month, or roughly $10,572 per year, before property taxes, insurance, and HOA dues.
Should I wait for mortgage rates to drop before buying an Eastside home?
No one can reliably predict rates. A better question is what monthly payment you can comfortably carry today. Across the NWMLS region, buyers currently have more inventory to choose from than at any point since 2014, and a buyer who later qualifies for a lower rate may be able to refinance, though that is never guaranteed. A lender and a neighborhood-level review of NWMLS data will show what waiting could cost or save in your situation.
How do higher mortgage rates affect Eastside home sellers?
Higher rates shrink the pool of buyers who qualify at a given price. NWMLS reported that across its region, for every 100 new listings in September, buyers went under contract on about 62 homes, down from about 80 a year earlier, and showings per listing fell to 4.2 from 5.2 across the NWMLS region. Sellers do best by pricing to current closed sales and by discussing options such as buyer credits or rate buydowns with their agent and lender.
Are Eastside home prices falling because of higher mortgage rates?
Prices are adjusting slowly. In September, the NWMLS median price was $625,000, down 0.9% from a year earlier, and 8 of 9 Eastside single-family areas had lower medians than a year ago, with Bellevue East flat. Economist Steven Bourassa of the Washington Center for Real Estate Research describes prices as showing downward stickiness, meaning they tend to fall more slowly than they rise. Medians in low-volume areas can swing widely from month to month.
Mortgage rate data: Freddie Mac Primary Mortgage Market Survey (national weekly averages), for the week ended October 8, 2026; earlier readings as cited by the Northwest Multiple Listing Service. Market statistics: Information and statistics compiled and reported by the Northwest Multiple Listing Service. Payment examples are hypothetical, for education only, and are not a loan offer, rate quote, or financial advice. Freddy Delgadillo is a real estate broker, not a mortgage lender; consult a licensed lender for a personalized quote.

500+ Eastside Transactions
CLHMS · CRS · ABR · GRI · CSP
425 Magazine & Seattle Times Featured
Bilingual English/Spanish
YOUR EASTSIDE MARKET ADVISOR
Let's Run Your Numbers Together
Buying? I'll build a payment-first plan around today's rates and show you where NWMLS data gives you room to negotiate in your neighborhood.
Selling? I'll price your home to current closed sales and walk through the buyer-incentive options that fit your goals.
Schedule a Consultation Call Freddy📞 Call/Text: (425) 941-8688
✉️ freddy@judahrealty.com
🌐 JudahRealty.com
📍 10237 Main Street, Bellevue, WA 98004